The Tax Conversations Every Business Owner Should Be Having Before June 30
Tax planning is a decision-making conversation, not a paperwork exercise. Here's how to approach it strategically.
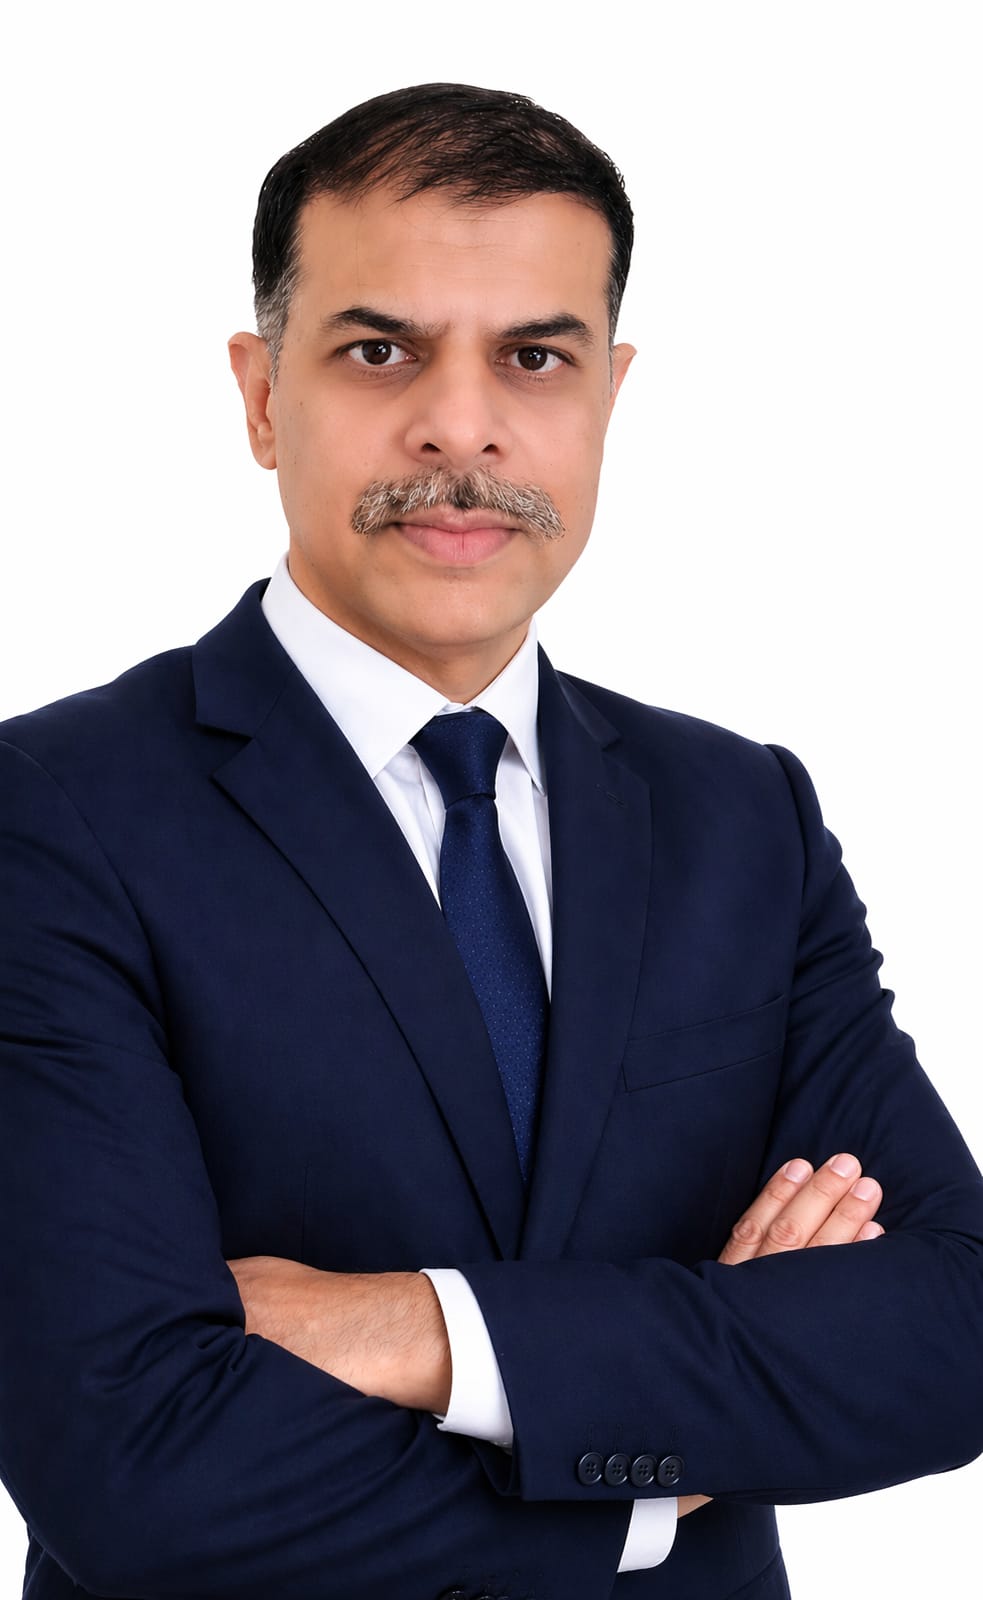
Anand Thakur, CA ANZ
Founder & Principal Advisor, WMB
Business owners don't call an advisor because they enjoy tax. They call because they want to feel in control. They want to know they haven't paid more than they need to, that they aren't going to be surprised in June, and that the decisions they make today aren't going to cost them money in five years. That is what real tax planning is — not paperwork, not compliance, not lodgement. It is the ongoing conversation about how money moves through your business, your family and your future.
In this article I have deliberately stayed away from legislation and focused on the conversations business owners should actually be having with their advisor — the ones that create long-term confidence, not just a smaller tax bill.
Tax planning is a decision, not a lodgement
Compliance is looking backwards. It is telling the ATO what already happened. That matters — but by the time compliance work begins, every important decision has already been made.
Planning is looking forward. It is deciding what will happen — how to structure income, how to time expenses, when to invest, when to draw, when to hold. Most of the value in tax planning is created in the decisions made months before June 30, not in the clever paperwork done in October.
By the time your accountant is lodging your return, the tax outcome has already been decided.
The five conversations you should be having every year
Every business owner should be having five recurring conversations with their advisor — ideally between March and May, well before the financial year closes.
1. Structure
Is your current structure still right for where your business and family are today? Structures that suited a solo tradie rarely suit a business turning over $2 million with a young family. Reviewing structure every few years is one of the highest-return conversations you can have — but only if it happens before the year ends.
2. Timing
Should you bring income forward, defer it, or spread it? Should a bonus be paid this year or next? Should an asset be purchased before or after 30 June? Timing decisions are usually worth more than deductions — and they are entirely in your control.
3. Wealth
How is business income being converted into long-term wealth? A profitable business that never converts profit into personal wealth is a business that stresses its owner for 30 years and leaves them with nothing to show for it. Superannuation, personal investments, property, debt reduction — these should all be part of the annual conversation.
4. Family
Are decisions being made in a way that considers the whole household — not just the business? Spouses, adult children, family trusts, education funding, protection. Business tax decisions rarely stop at the business owner.
5. Exit
Every decision you make now affects what you keep when you eventually sell or hand it over. Small structural choices made years before a sale often make a bigger difference to the final result than the sale price itself.
When strategic planning pays off most
There are five moments in a business's life when a proper planning conversation is worth many times what it costs.
- After a big year. Unusually strong profits often need active planning to avoid an oversized tax bill and a wasted opportunity.
- Before a major purchase. Buying an asset, a building or a vehicle without a five-minute conversation about timing and structure can cost tens of thousands.
- Before hiring. Wages, super, workers' compensation, PAYG — hiring is a financial decision, not just an operational one.
- Before selling. The years leading up to a sale are where most post-sale tax outcomes are actually decided.
- Before restructuring. Moving into a company, adding a trust or bringing in a partner should never be a rushed decision.
Superannuation as a wealth strategy
Business owners often think of super as a tax tool. It is more useful to think of it as a wealth tool with tax benefits. Consistent contributions — even modest ones — made every year for 15 or 20 years almost always outperform the last-minute contributions many owners make in the final week of June.
The strongest wealth outcomes I see aren't from clever strategies. They are from consistency: the owner who quietly puts $25,000 a year into super for two decades finishes miles ahead of the one who talks about it every year and never does it.
Signs your tax planning isn't working for you
If any of the following are true, tax is being done to your business rather than with it.
- You're regularly surprised by the amount you owe.
- Your accountant only speaks to you when they need documents.
- You've never had a strategic conversation between July and April.
- Structural decisions are being made because "that's how it's always been".
- Business income has grown but your personal wealth hasn't.
Frequently Asked Questions
When is the best time to do tax planning?
Ideally between March and May, before the financial year closes. Once June 30 has passed, most of the decisions that shape your outcome are locked in and only compliance work remains.
Is tax planning worth it for a small business?
Yes — often more so than for a large one. Small businesses tend to have simpler numbers but larger relative outcomes: a small structural change can compound into a big personal wealth difference over a decade.
How often should I review my business structure?
Every three to five years, or any time the business changes materially — new partners, significant growth, property acquisition, family change, or planning for exit. A structure that suited an earlier stage rarely fits the next one.
What's the difference between tax planning and tax minimisation?
Tax minimisation focuses purely on paying the smallest number. Planning focuses on the best long-term outcome for the business, the family and the owner's future — which usually means paying the right amount of tax at the right time, with no surprises.
Next Steps
What Should You Do Next?
- 1
Book a strategic tax planning conversation for the March–May window this year, not July.
- 2
Ask your advisor to review your business structure against where you are today, not where you started.
- 3
Set your superannuation strategy as an automatic monthly habit — not a June decision.
- 4
Have a one-hour conversation about what a good exit could look like, even if it feels a decade away. Those decisions start now.
About the Author
Anand Thakur, CA ANZ
Founder & Principal Advisor · WMB — We Mean Business
Anand is a Chartered Accountant with more than 30 years of experience helping Australian business owners at every stage of their journey — from launching a first business to planning succession. He founded WMB to make experienced business advice accessible across Australia through a virtual advisory model.
Let's Start The Conversation
Have a question about your own business?
WMB works with business owners across Australia through secure virtual meetings. A short conversation is often the best place to start.
Continue reading